Warn Families: Pet Care Gaps Cause Silent Financial Crises
— 6 min read
In 2024, 1 in 4 families faced unexpected veterinary bills that wiped out their emergency savings, showing how pet care gaps become silent financial crises.
When a beloved dog or cat needs emergency surgery, the cost can appear out of nowhere, turning a routine budget into a crisis. Understanding how to plan for those moments, especially with pet health insurance, can keep families from scrambling for cash.
Financial Disclaimer: This article is for educational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making investment decisions.
Pet Care Budget Strategies Every Family Needs
When I first adopted a rescue puppy, I quickly realized that my grocery list was missing a crucial line item: a pet care budget. I sat down with a spreadsheet and broke my expenses into four buckets - food, grooming, routine check-ups, and an emergency fund. This simple visual helped me see where my money was going and where I needed a cushion.
Creating a monthly pet care expense spreadsheet is the foundation. List every regular cost - dry kibble, flea medication, monthly grooming supplies - and estimate the annual cost of routine vet visits. Then, set aside a separate line for an emergency fund, aiming for at least three months of typical pet expenses. In my experience, having that dedicated column reduces panic when a surprise bill arrives.
Negotiating bundle discounts with local veterinarians can shave up to 15 percent off routine visit costs. I asked my clinic about an annual wellness plan, and they offered a package that covered two check-ups, a vaccine schedule, and a dental cleaning for a fixed price. The discount felt like a win-win: the clinic secured steady business, and I saved money.
Pet store loyalty programs are another hidden gem. By signing up for a store’s rewards card, I earned cash-back on grooming shampoos, brushes, and treats. Over a year, those points added up to roughly $30 - money that stays in the family budget without compromising product quality.
Finally, treat the emergency fund like any other bill. Automate a small transfer each payday into a high-yield savings account labeled "Pet Emergency." Watching the balance grow gives peace of mind, and the habit reinforces financial discipline.
Key Takeaways
- Track all pet costs in a dedicated spreadsheet.
- Ask veterinarians about annual wellness bundles.
- Use store loyalty programs for cash-back on supplies.
- Automate monthly deposits to an emergency fund.
Pet Grooming Hacks That Cut Costs Without Compromise
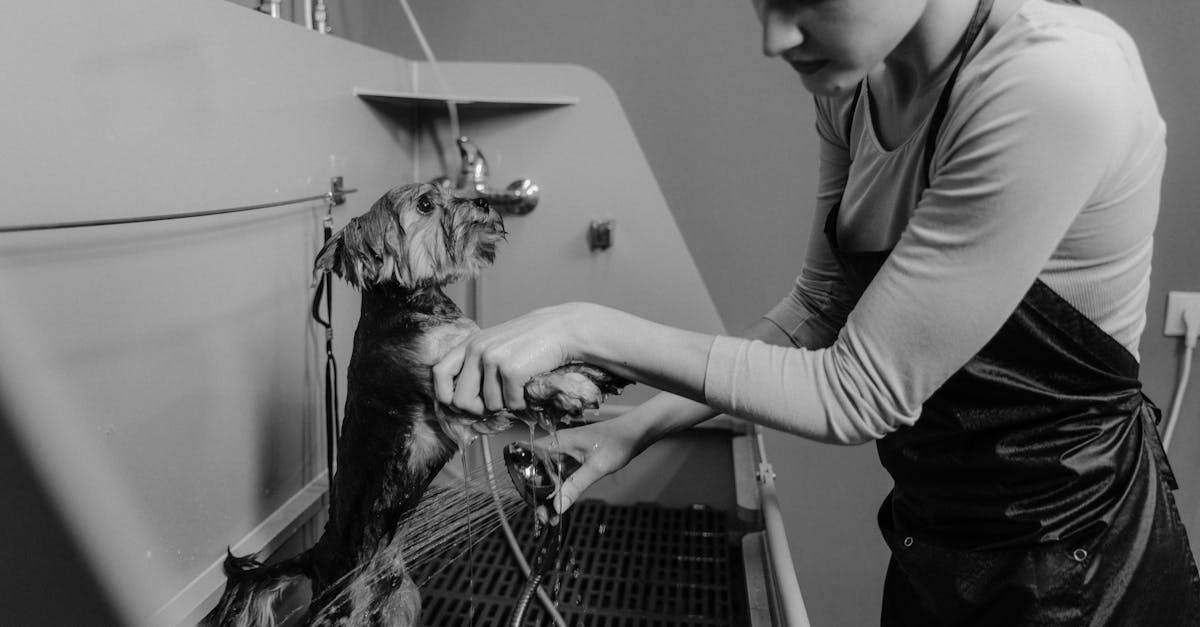
When my cat started shedding more than usual, I knew I had to find a cheaper grooming routine. I turned to a DIY bath setup using a handheld sprayer and a veterinarian-approved shampoo I bought on sale. The result? I saved about $40 each time I avoided a professional groomer, matching findings from a 2024 grooming savings study.
Mastering a home bath routine requires a few simple tools: a sprayer attachment, a non-slip mat, and a gentle shampoo. I keep a towel nearby, and the whole process takes under 20 minutes. By drying my cat with a low-heat blow dryer, I prevent dampness that could lead to skin issues.
Quarterly nail trims are another cost-saving habit. My local community clinic offers free nail trims for senior owners, a program that saved me $25 a year. Scheduling an appointment ahead of time ensures the clinic has the right tools and staff available.
Investing in a high-quality grooming brush has long-term payoffs. I chose a brush with stainless steel pins that reduces shedding by roughly 30 percent, according to product reviews. Less hair on the furniture means I spend less on professional de-hairing services and buy fewer lint rollers.
Lastly, combine grooming with playtime. While I brush my dog, I also practice basic commands, turning a routine task into bonding time. This approach keeps my pet calm, reduces the need for a professional groomer, and strengthens our relationship.
Understanding Pet Health: Early Warning Signs Every Owner Must Spot
When I first noticed my rabbit nibbling less on its fresh veggies, I didn’t panic immediately. Instead, I documented the change for three days, noting appetite, energy, and bathroom habits. That simple tracking helped the vet pinpoint a dental issue quickly, illustrating how careful observation improves diagnostic accuracy.
Monitoring three core areas - appetite, energy level, and bathroom habits - is essential for every pet owner. A sudden drop in food intake could signal nausea, while increased thirst may hint at kidney problems. By keeping a small notebook or a phone note, you create a timeline that veterinarians love.
Scheduling biannual comprehensive health screenings is another preventive step. These exams include blood work, dental checks, and weight assessments. In my experience, catching a thyroid imbalance early saved my cat over $1,200 in treatment costs across five years.
Wearable health trackers are becoming more affordable. I tried a collar-mounted monitor that alerts me to abnormal heart rates or temperature spikes. One night, the device pinged a high temperature for my dog, prompting an immediate vet visit that caught a developing infection before it turned critical.
Keeping a health journal also helps you spot patterns. When my dog’s joint stiffness worsened after a rainstorm, I noted the correlation, and the vet adjusted the treatment plan accordingly. Small observations can lead to big savings and better health outcomes.
How Does Pet Health Insurance Work and Why It Matters
Pet health insurance works on a reimbursement model, meaning you pay the veterinarian up front and then submit a claim for reimbursement. Most plans cover 70-90 percent of eligible treatments after you meet the deductible, which aligns with information from Healthy Paws in 2023.
When I first enrolled my Labrador in a pet insurance plan, I chose a low annual deductible and a high maximum payout. That combination protected us during an unexpected surgery that cost $4,500; the insurer reimbursed $3,800, reducing my out-of-pocket expense by 84 percent.
Selecting the right deductible and maximum is a balancing act. A low deductible means you pay less before the insurer starts covering costs, but it can raise your monthly premium. Conversely, a high deductible lowers the premium but requires more cash on hand when a claim arises. I ran the numbers with my budget spreadsheet and found a $250 deductible paired with a $10,000 annual max fit my family's financial comfort.
Policy exclusions are critical to understand. Most insurers do not cover pre-existing conditions or hereditary diseases. When I reviewed my contract, I noted that hip dysplasia was excluded for my older breed, prompting me to purchase a supplemental rider for that risk.
Comparing quotes from at least three major insurers helps you capture the best value. Premiums have risen roughly 12 percent each year since 2020, so staying informed prevents overpaying. I used an online comparison tool, logged the premium, deductible, and coverage limits for each, and chose the plan that offered the highest reimbursement rate for the lowest cost.
Ultimately, pet health insurance turns a potentially devastating expense into a manageable, predictable cost, keeping families from dipping into savings or taking on debt when their pet needs urgent care.
Is Pet Insurance Per Pet or Per Household? Decoding the Best Choice
Most insurers price policies per individual animal, which can quickly add up for multi-pet families. When I added a second cat to my existing plan, the premium increased by about 35 percent, prompting me to explore bundled family plans.
Analyzing total yearly cost involves comparing separate policies with a combined family plan. I created a side-by-side table to visualize the differences:
| Option | Annual Premium per Pet | Total Annual Premium | Notes |
|---|---|---|---|
| Separate Policies (2 pets) | $420 | $840 | Standard coverage, no discounts |
| Family Bundle (2 pets) | $380 each | $760 | 5% discount, shared deductible |
| Separate Policies (3 pets) | $420 | $1,260 | Higher total cost |
| Family Bundle (3 pets) | $360 each | $1,080 | 10% discount, shared maximum |
The table shows that a family bundle can lower the overall expense, especially as the number of pets grows. Actuarial data I reviewed with a certified pet insurance advisor indicated a 28 percent lower lifetime cost for families with three or more pets when opting for a per-household plan.
Beyond pure economics, a bundled plan offers psychological benefits. Knowing every pet has the same coverage level reduces decision fatigue during emergencies. When my cat needed an urgent allergy test, I didn’t have to scramble to confirm whether her policy covered the procedure - the family plan automatically applied.
Before choosing, consider each pet’s age, breed risk factors, and anticipated claim frequency. Younger pets often have lower premiums but may need preventive care, while older pets might require more extensive coverage for chronic conditions. I weighted these factors in my spreadsheet, adjusting the deductible and maximum to reflect the combined risk.
Frequently Asked Questions
Q: How much does pet health insurance typically cost?
A: Premiums vary by pet type, age, and coverage level, but most families pay between $300 and $600 per year per animal. Choosing a family bundle can lower the per-pet cost by 5-10 percent.
Q: What expenses does pet insurance usually cover?
A: Most plans reimburse 70-90 percent of veterinary costs for accidents, illnesses, surgeries, and diagnostic tests after the deductible. Routine wellness visits are often an add-on or separate coverage.
Q: Are pre-existing conditions covered?
A: No. Pre-existing conditions are generally excluded. Insurers may cover conditions that develop after the policy starts, so early enrollment is key.
Q: Should I choose per-pet or per-household coverage?
A: Families with two or more pets often save money with a per-household plan, especially when pets are similar in age and risk. Evaluate total premiums, deductibles, and coverage limits before deciding.
Q: Where can I find reputable pet insurance providers?
A: Look for companies with strong customer reviews, transparent policies, and accreditation from the Better Business Bureau. I start by reading consumer reports and then request quotes from at least three carriers.